This manual is for BUS FPX 4060 Assessment 3, start to submission. Internal Control and Accounting for Assets asks you to work problems and explain concepts on protecting and recording a company's assets: internal control principles, especially over cash, bank reconciliations, accounts receivable and the allowance for doubtful accounts, and long-lived assets, including cost, depreciation methods and disposal. The grade turns on correct entries and clear explanation of why controls and estimates matter. Below is the method our tutors use, a structure that maps to the criteria, and an annotated sample excerpt. Prefer to hand it off? A premium original sample for this exact assessment comes back in 24 to 48 hours, revised free until it meets the guide. Capella's catalog lists the course as BUS-FPX4060, and some courserooms print BUS4060; both point to this same Assessment 3. In current courserooms this assessment typically appears as "Internal Control and Accounting for Assets".
One honesty note before the manual: Capella revises courses and scoring guides over time, so always write to the exact scoring guide attached to your assessment in the courseroom. The course identity above is verified on capella.edu; the method and structure below are our tutors' approach to it, not Capella's official rubric text.
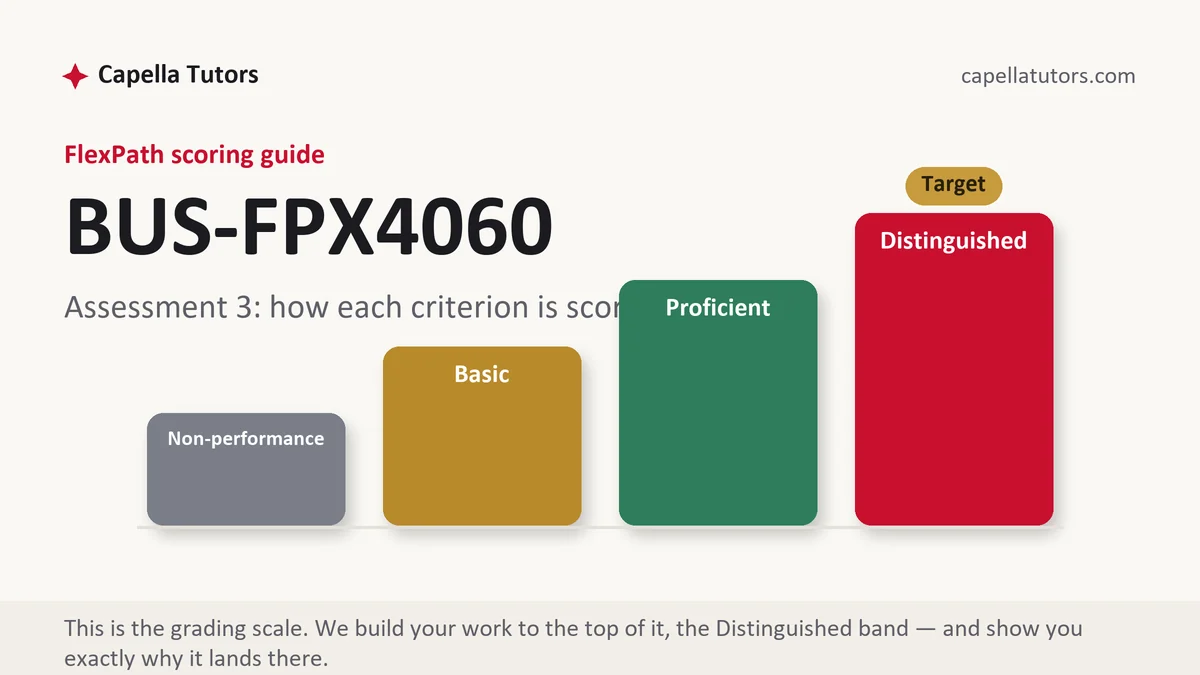
How BUS FPX 4060 Assessment 3 is scored
FlexPath does not use letter grades. Each criterion in the scoring guide lands on one of four levels, and the level descriptions are the real writing brief:
| Level | What it means on a asset accounting problem set |
|---|---|
| Distinguished | The asset accounting problem set is specific to the organization or case, applies course concepts accurately with credible sources, and ends in justified conclusions or recommendations. |
| Proficient | The asset accounting problem set is accurate, but the application or recommendations are general. |
| Basic | The asset accounting problem set describes concepts with little application. |
| Non-performance | A required part of the asset accounting problem set is missing. |
Use the problem set in your courseroom and show every entry and calculation.
The BUS FPX 4060 Assessment 3 method, step by step
-
Internal control principles
Segregation of duties, authorization, documentation, physical controls, reviews.
-
Bank reconciliation
Adjust both bank and book balances and record the book adjustments.
-
Receivables
Estimate bad debts with the allowance method and record write-offs.
-
Long-lived assets
Capitalize cost, including costs to get the asset ready for use.
-
Depreciation
Straight-line, declining balance and units of activity.
-
Disposals
Record gains or losses on sale.
A structure that maps to the criteria
The problem set or template in your courseroom sets the questions; show your work for each.
| Section | What it must do | Guide |
|---|---|---|
| Internal control | Principles and examples. | answers |
| Cash and bank reconciliation | Reconciliation and entries. | worked problem |
| Receivables and bad debts | Estimates and entries. | worked problem |
| Long-lived assets and depreciation | Calculations and entries. | worked problem |
Annotated sample excerpt
An original model excerpt from our team, written to show the register that reaches the top of the guide. Learn the moves, then write your own version.
The book balance must be adjusted for items the bank knew about first: a 45 dollar service charge and a 600 dollar customer check returned for insufficient funds both reduce the book balance.1 Outstanding checks and a deposit in transit adjust the bank side instead, since the company has already recorded them.2 Only the book-side adjustments need journal entries, which is why the reconciliation also serves as a control, catching errors and unrecorded items each month.3
- 1Identifies book-side adjustments correctly.
- 2Places bank-side items correctly.
- 3Explains which items need entries and why reconciliation is a control.
The full premium sample for your exact assessment, written fresh to your scoring guide and topic, is free to request. Study it, revise it into your own voice, and submit work you understand.
The five mistakes that cost Distinguished
- Definitions without application. Apply each concept to the organization or case.
- No sources. Cite credible business sources.
- Vague recommendations. Make them specific and justified.
- No work shown. Show every step.
Pre-submission checklist
- Control principles
- Bank reconciliation
- Receivables and bad debts
- Long-lived asset cost
- Depreciation
- Disposals
Want the asset accounting problem set written?
Send the scoring guide and any materials from your courseroom. Our team returns a premium original asset accounting problem set in 24 to 48 hours, revised free until it meets the guide.